Central government debt in Burkina Faso stands at 8,731.5 billion FCFA, up nearly 4,000 billion since 2020
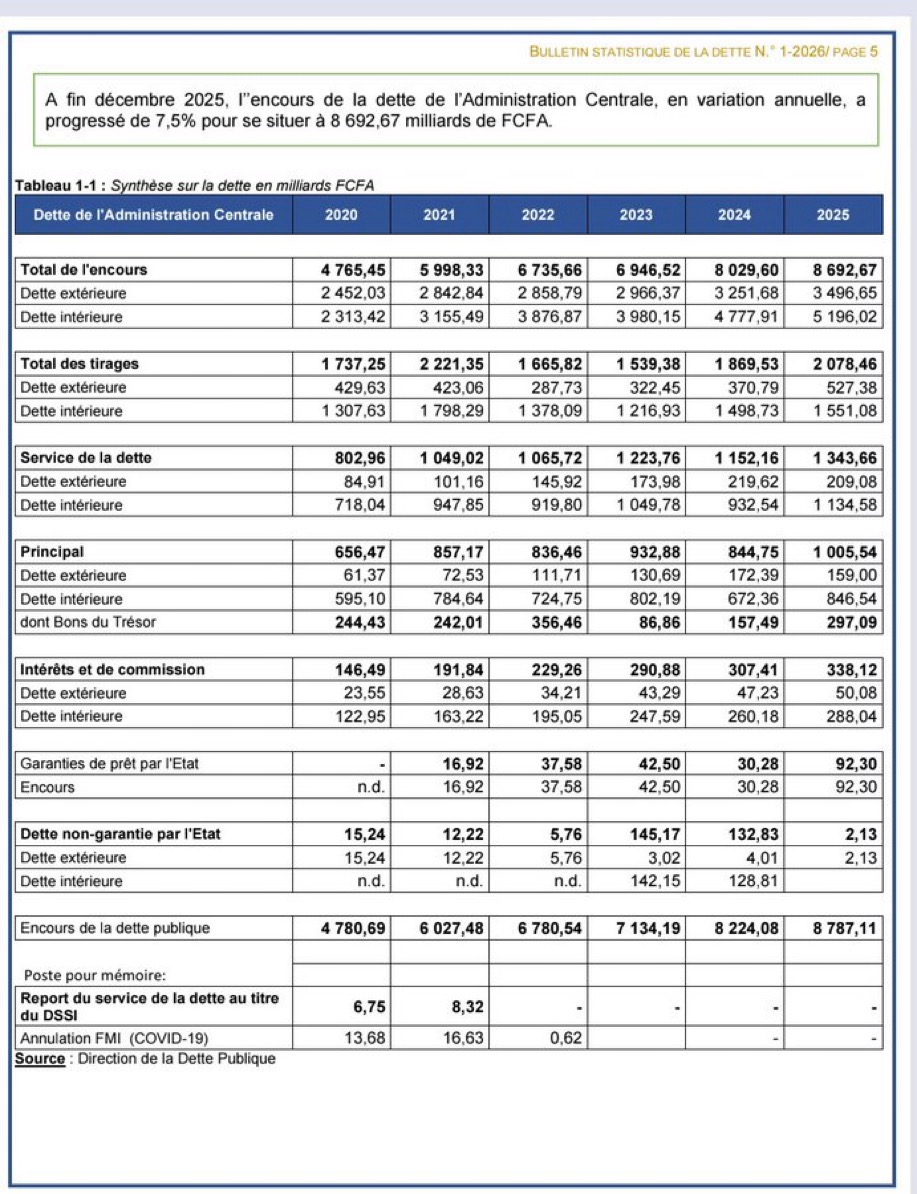
Burkina Faso’s central government debt stood at 8,731.5 billion FCFA at the end of March 2026, the latest Treasury statistics show. At the close of 2020, the outstanding stock was 4,765.45 billion FCFA. The increase recorded over that period approaches 4,000 billion FCFA, a figure that complicates the anti-borrowing doctrine consistently promoted by Ibrahim Traoré.
The president frequently argues that Burkina Faso must rely on its own capacities and has no need to borrow in order to build its development. That position is presented as a break with past practice: less external dependence, greater economic sovereignty, and development financed from national resources. The public debt figures, however, call for a more measured reading of that claim.
The figures behind the doctrine
The progression of the debt is documented in the Treasury’s statistical bulletins, and it has been continuous.
- End of 2020: 4,765.45 billion FCFA
- End of 2021: approximately 6,107 billion FCFA
- End of 2025: 8,692.67 billion FCFA
- End of March 2026: 8,731.5 billion FCFA
Within a few years, the country moved from an indebtedness level below 5,000 billion FCFA to more than 8,700 billion FCFA.
Why the domestic tilt deserves scrutiny
The composition of the debt is as significant as its volume. At the end of 2025, close to 60 percent of central government debt was domestic, mostly in the form of Treasury bills and bonds. Domestic debt alone amounted to roughly 5,196 billion FCFA.
This matters because internal financing is not free of charge. The principal must be repaid, and interest paid along with it.
Debt service climbs 31.5 percent in a year
In the first quarter of 2026 alone, debt service reached 407.1 billion FCFA, an increase of 31.5 percent compared with the same period a year earlier.
Sovereignty has a cost of its own
A policy of economic sovereignty is a legitimate position to defend. But sovereignty is not measured solely by the refusal of certain partners or by declarations about financial independence.
It is also measured by a state’s capacity to raise revenue on a lasting basis, to control its spending, to finance its investments and to contain the weight of debt service.
Burkina Faso holds substantial mining resources, gold in particular. The existence of those resources does not, however, automatically mean that the state has enough liquidity to fund every ambition without resorting to borrowing.
Moderate risk, persistent vulnerabilities
In its 2026 analysis, the International Monetary Fund classifies Burkina Faso at a moderate risk of debt distress while judging the debt sustainable over the medium term. The institution nonetheless points to several vulnerabilities: the risk attached to refinancing domestic debt, dependence on gold export earnings, and the security situation.
It would therefore be excessive to present this debt increase as mechanical proof that Burkina Faso is insolvent. The available data do not support such a conclusion.
By the same token, it would be difficult to argue that the country has developed in recent years without significant recourse to borrowing. The numbers tell a different story.
Borrowing is not, in itself, mismanagement
The central issue is not whether a state borrows. Public debt is not automatically synonymous with poor governance. A state may borrow to finance infrastructure, support investment, respond to a security crisis or maintain public spending when revenue falls short.
The essential question is different: what are the new loans used for, at what cost are they contracted, and what future repayment capacity do they generate?
The contradiction the government must address
The government can highlight its investments, its military effort, its infrastructure or its social policies. Those expenditures must nevertheless be weighed against the evolution of the debt.
Between the end of 2020 and the first quarter of 2026, the outstanding debt of the central administration rose by close to 4,000 billion FCFA.
The question that remains is simple, though politically and economically weighty: if Burkina Faso does not need to borrow in order to build itself, how can an increase of several thousand billion FCFA in public debt over that period be explained?
It is on this apparent contradiction between the doctrine of financial sovereignty and the trajectory of the public accounts that Ibrahim Traoré’s government will have to provide precise answers: how much was borrowed, from whom, at what rate, to finance which projects, and with what measurable results for the population?
In public finance, slogans may persuade. The figures remain to be explained.